Not content with the standard carried interest as they seek to hang onto their most prized investments, some private equity firms are now demanding “super carry.”
In several new funds that the firms are creating to hold onto certain investments — known as single-asset continuation vehicles — dealmakers are demanding a bigger share of the future gains.
Provisions for super carry — which is anything exceeding the standard 12% to 20% range for carried interest — were included in almost a third of new single-asset continuation vehicles created in the first half of 2026. That’s almost triple the level from a year earlier, PJT Partners Inc. said in a report.
When Parthenon Capital Partners set out to extend its control of Kroll Bond Rating Agency, for instance, the private equity firm sought a higher share of profits to manage a new fund that would hold the prized portfolio company.
While multiple investors balked at the terms, HarbourVest Partners finally agreed to the deal, allowing Parthenon to raise more than $1.7 billion for the single-asset continuation vehicle.
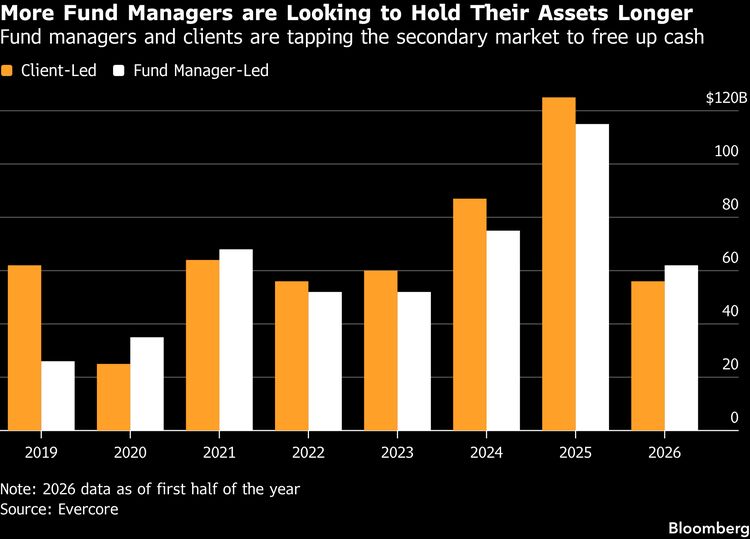
The growth of super carry for secondary transactions shows that even as a majority of private equity funds struggle to exit investments, the most sought-after deals still give leverage to the manager.
The super carry deals could offer a reprieve for rainmakers who are struggling to earn any carried interest at all from some funds as higher interest rates have crimped dealmaking. That has prompted some to jump to firms with more profitable funds, become independent sponsors that focus on one deal at a time or even quit the industry altogether.
Just because buyers agree to a super-carry structure doesn’t mean managers will be able to collect the higher payouts. They first need to hit certain targets, and triggers vary deal-by-deal. Some backers will insist on an internal rate of return of 30% or a return on invested capital of at least three times, or a combination of both.
One dealmaker said his firm’s internal estimate is that only a fraction of such agreements will result in triggering super carry.
“Sponsors should have an incentive to continue to maximize value above certain levels within the portfolio performance,” said David Perdue, a partner in PJT’s strategic advisory group.
Privately, buyers say they still may be willing to allow asset managers to take a greater share of profits because competition is stiff for the most coveted assets. Some also relent because of a fund manager’s track record or deep knowledge about an underlying asset.
While some potential backers balked last year at Percheron Capital’s request for super carry on a $1.62 billion fund for Big Brand Tire & Service, it persuaded other investors to go along, including Blue Owl Capital Inc., Iconiq and Warburg Pincus.
“In general, we support structures that align sponsors with investors, paying sponsors more only when investors earn more,” a spokesperson for Blue Owl said in an emailed statement, while declining to comment about a specific transaction.
Leonard Green & Partners’ Sage fund, which backs single-asset continuation funds, agreed to a super-carry structure for Falfurrias Management Partners’ deal on Crosslake, a technology advisory firm.
Accel-KKR, which already takes super carry on its primary funds, persuaded buyers in its continuation funds to agree to a premium as well, albeit with a higher threshold for returns, according to people familiar with the matter.
Not all money managers can persuade investors to pay them super carry. Lightspeed Venture Partners, which is seeking $600 million for a multi-asset continuation fund, proposed super carry of 25% for the deal, but lead buyer Coller EQT batted that down, according to people familiar with the negotiations.
Representatives for the firms declined to comment or didn’t reply to messages seeking comment.