Bond investors are demanding the most compensation to own French bonds over Italian ones since the founding of the euro.
The spread between the two nation’s benchmark 10-year bond yields hit a record at 30 basis points on Friday. Until last year, Italy was considered the riskier of the two, with higher borrowing costs than France.
Now, investors are punishing France for not cutting its budget deficit as much as hoped and for showing no signs of reducing its 117.6% debt-to-GDP ratio. Money managers are also asking for a higher yield to compensate for the political uncertainty ahead of a presidential election next April that could pit the far-right against the far-left.
At the same time, Italian bonds are getting rewarded for years of painful austerity that reduced government debt levels and boosted economic growth. While the nation’s bonds were hit hard during the recent selloff, investors say the moves were unjustified.
“We see opportunity in some of the European markets which widened alongside France in recent weeks,” said Alex Everett, who manages Aberdeen Investment Management’s euro government bond fund. “Italy, Spain and other smaller markets can outperform, given the wider strength of the integrated European Union, and better debt trajectories.”
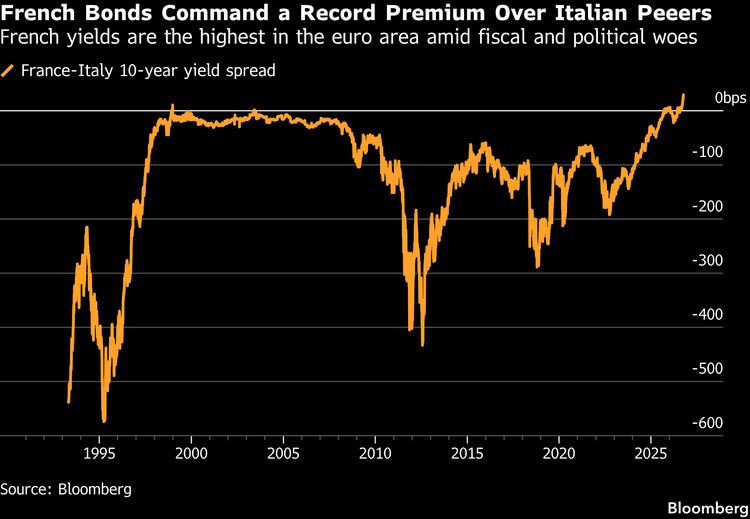
French bonds underperformed those of other nations in the region too, but the move against Italy draws attention because the latter was considered for years a bellwether for euro-area sovereign risk. Italian 10-year yields were once more than 400 basis points higher than French debt in July 2012 at the height of the eurozone debt crisis.
But things have flipped, and France is now at the heart of a selloff in European bonds. The yield spread between France and Germany, the region’s safe haven, has widened to levels last seen in the euro debt crisis, past 150 basis points last week. It narrowed as much as five basis points to 135 basis points on Friday as the selloff stabilized · .
Read more: France’s Decades of Deficits Bring Home a Painful Risk Premium
Investors have used the recent selloff to pick up cheaper debt from the likes of Italy and Spain, according to Irina Kurochkina, portfolio manager at Aegon Investment Management. Still, they are largely steering clear of France, she added.
“It does make some other names more attractive after the widening, especially periphery countries with a better budget position and GDP outlook,” she said. “France is is getting cheap enough to reduce short positions somewhat, but we are not ready to move it to neutral given the volatility on the back of budget discussions and escalating protests.”