The biggest technology leaders dragged down US equity benchmarks as worries OpenAI’s revenue will disappoint bled through to other artificial intelligence bets and chipmakers.
The Nasdaq 100 declined 1.4% , its worst one-day drop in seven weeks, while the S&P 500 Index fell 0.5% . The Philadelphia Semiconductor Index plunged 3.4% as Wall Street’s fear gauge, the Cboe Volatility Index, rose for the second day in a row.
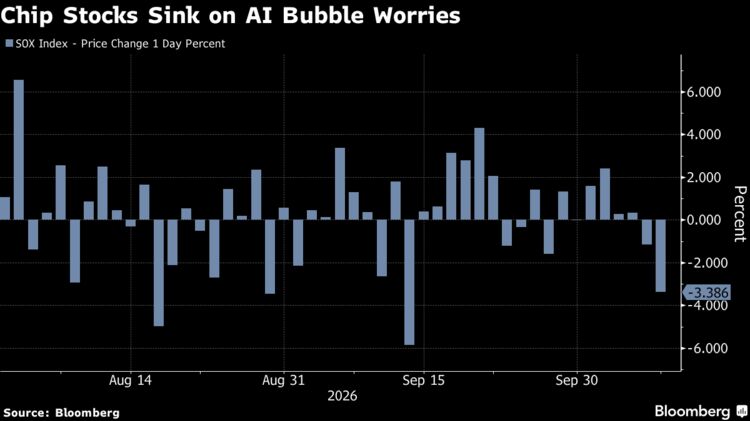
A selloff in tech and AI-linked stocks deepened midday amid multiple bearish headlines. The Financial Times reported OpenAI’s annualized revenue is $20 billion less than previously signaled. Oracle Corp. slid following a report it was trucking natural gas to server farms as a workaround to power bottlenecks.
A barometer of smaller US firms avoided the worst of the selling, but the Russell 2000 Index is closing in on a 10% drop from its all-time high. The benchmark is also testing its 200-day moving average, a key technical level.
“My biggest surprise is the tech selloff remains concentrated, with more than two-thirds of S&P 500 constituents higher and small caps close to flat,” said Chris Murphy, co-head of derivatives strategy at Susquehanna International Group. “Strength in staples and low-volatility stocks points to rotation toward defensives rather than broad-based equity selling.”
The 10-year Treasury yield rose to 5.2%, pressuring rate-sensitive sectors amid renewed energy-supply risks and worries over elevated interest rates.
Concerns around energy supply also continue to buffet investors. Oil advanced after a report that the White House asked the Pentagon to prepare potential strike options against Iran that could be carried out before the midterm elections. Hurricane Isaias is also developing in the Gulf, adding to the concerns.
Federal Reserve Governor Christopher Waller’s hawkish tone didn’t help sentiment. Waller said additional rate increases will probably be necessary to bring inflation under control, while noting policymakers have flexibility over when to act and don’t necessarily need to raise rates at consecutive meetings.
Other reactions to AI-related results were mixed. Samsung’s record preliminary quarterly results failed to satisfy the most bullish expectations, while TSMC delivered 51% sales growth. The contrast comes as investors prepare for a US earnings season in which AI spending and demand are expected to remain dominant themes.
Deutsche Bank strategists expect third-quarter earnings growth to remain at a historically elevated 34% year-on-year pace, with AI-driven demand helping sustain earnings growth of about 54% for megacap technology companies.
A larger share of US companies is also expected to surpass third-quarter earnings estimates than in the prior quarter, according to Citigroup strategists Richard Schlatter and David Chew. Their model projects 66% of Russell 1000 companies will beat estimates, compared with just over 60% in the second quarter. Technology is expected to notch the most earnings beats.
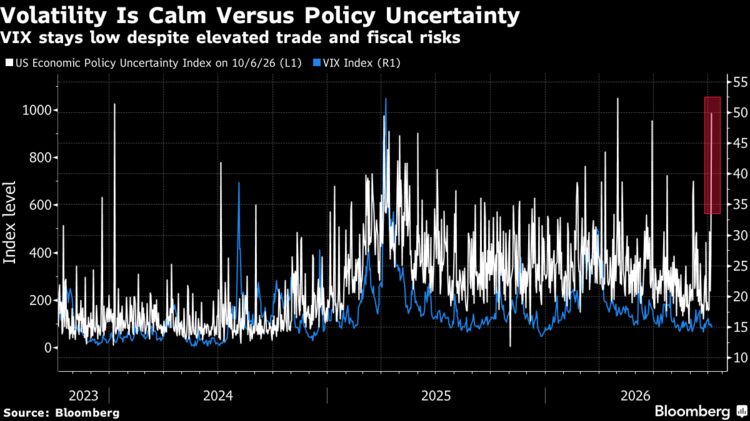
The backdrop for policy has become increasingly uncertain. An index tracking US economic policy uncertainty has posted one of its sharpest increases in three years, even as market volatility remains relatively muted.
Unease about the upcoming elections is swaying the market, according to Manulife John Hancock Investments strategist Matt Miskin. He notes that banks and industrials, which are sectors that “typically do better under Republican policies,” have recently weakened. That may signal the market is “pricing in a bit more of a blue wave.”
Banks are also under pressure from credit-card, auto loan and mortgage rates that are all near 20-year highs, he said. Lenders can benefit as “higher yields can lead to better revenues, but they can also lead to a tipping point where consumers just can’t pay these kinds of loans,” he said.
In corporate news, Broadcom Inc. is already considering another large-scale transaction after launching $60 billion of debt financing to support Anthropic PBC’s AI build-out. And SK Hynix Inc.’s Solidigm has selected lead banks for a planned US initial public offering next year, according to people familiar with the matter.
Retail stocks were in focus Thursday after PepsiCo Inc. cut its profit forecast, saying its recovery in North America is taking longer than anticipated. And denim company Levi Strauss & Co. posted the slowest growth in its direct-to-consumer channels since late 2022 — in part due to a marketing misstep — while raising its full-year earnings outlook.
Chipotle Mexican Grill Inc. shares jumped 6% after the Financial Times reported that Starbucks Corp. has worked with advisers in recent months on a takeover proposal for the burrito chain. Palantir Technologies Inc. edged higher after Goldman Sachs upgraded the stock to buy from neutral, citing its underperformance this year. And Devon Energy Corp. shares rose 2.17% after it agreed to sell its Eagle Ford assets to Crescent Energy for $4.22 billion in cash.
Sectors in Focus
- Watch US insurers, utilities and home-improvement retailers as Hurricane Isaias develops and the storm moves toward the Gulf Coast. Oil and gas producers are shutting wells and evacuating personnel along the storm’s projected path.
- Keep an eye on energy stocks as oil prices surged on tanker attacks in the Middle East.
- Data-center companies are also in focus after a sharp drop in demand for an Nvidia-backed data-center operator’s IPO exposed new vulnerabilities in the AI financing boom. A planned $5.5 billion listing for Australia’s Firmus Grid Ltd. is under pressure after the offering failed to attract sufficient investor support at the marketed A$11 share price, according to people familiar with the matter.
- Watch bank stocks as Goldman Sachs and Wells Fargo were rated buys by a TD Cowen analyst, while Morgan Stanley was rated a hold on valuation.