The S&P 500 is poised to open just shy of an all-time high as traders weigh the prospect of solid results in a busy week for corporate earnings against the risk of escalating tensions in the Middle East.
S&P 500 contracts were little changed after the index ended last week within a whisker of record. Brent crude swung between gains and losses amid concerns over repeated Houthi attacks on Saudi Arabia · from neighboring Yemen. Traders were also assessing · President Donald Trump’s claim of an “energy ceasefire” between Russia and Ukraine.
Treasury futures nudged lower, with the cash market closed for Columbus Day in the US. Worries over political deadlock on fiscal policy sent French yields rising again. The dollar barely budged. Bitcoin mostly held gains following a three-day rebound. Chipmakers fell in early US trading.
Wall Street’s biggest banks are expected to unveil a quarterly stock-trading haul of $19 billion when the likes of JPMorgan Chase & Co. and Citigroup Inc. unofficially kick off the earnings season on Tuesday. Artificial-intelligence heavyweights will come under the spotlight later in the week when ASML Holding NV in Europe and Taiwan Semiconductor Manufacturing Co. report.
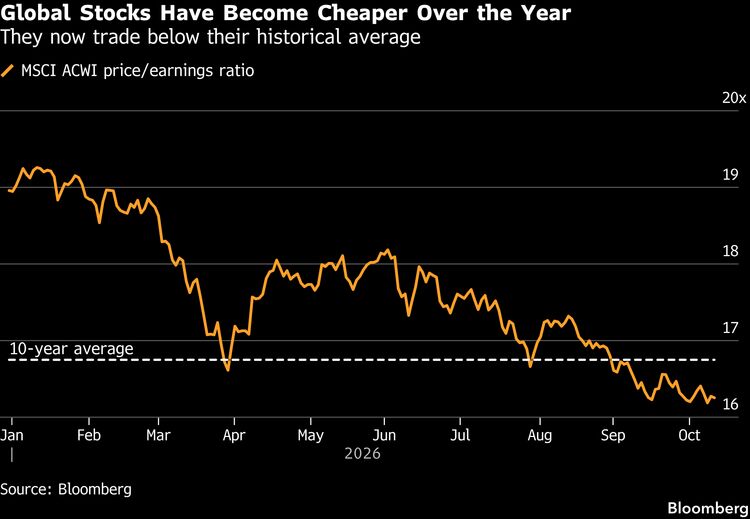
Goldman Sachs Group Inc. strategists including Christian Mueller-Glissman said the team turned overweight stocks for the next three months on expectations for strong earnings growth and a recent valuation derating.
“Double-digit earnings growth has so far helped offset the negative impact of higher rates,” said Vincent Juvyns, chief investment strategist at ING in Brussels. “The earnings season will be important in determining whether the bull market has further room to run.”
Traders are banking on an uplift from earnings after weeks of elevated oil prices and global bond yields at their highest levels in decades. Inflation data and a scheduled speech by Federal Reserve Chair Kevin Warsh will also inform expectations for the interest-rate path at a time when money markets are pricing another US rate hike by December.
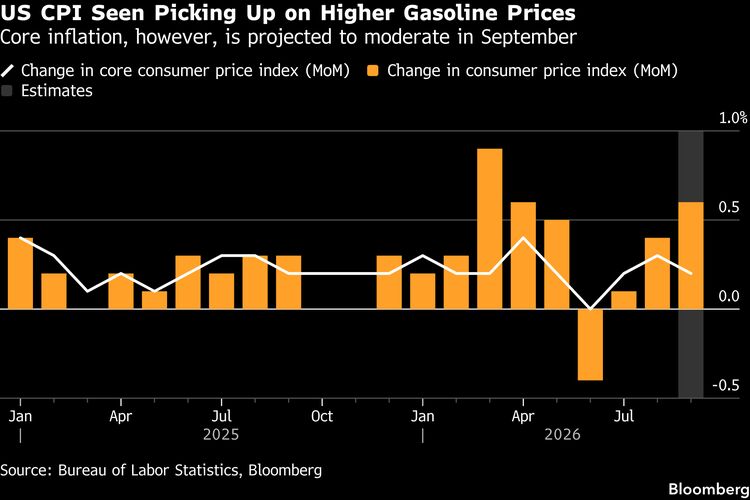
The closely watched consumer price index, due for release Wednesday, is seen rising 0.6% in September after a 0.4% increase a month earlier, based on the median projection in a Bloomberg survey. That would mark the largest advance in five months. Excluding fuel and food, the so-called core measure probably rose 0.2%, a step down from August.
“The contrast between a fuel-driven headline acceleration and a softer underlying core print will clearly be important for the Fed, particularly given recent messaging that further tightening may be needed but is not urgent,” noted Jim Reid, global head of macro research at Deutsche Bank AG.
What Bloomberg’s Strategists Say...
“US equities are primed to make fresh highs this week as financials kick off third-quarter earnings season. Rising rates are placing a higher hurdle that most stocks are failing to clear, yet robust tech results should keep headline index momentum intact.”
— David Savage, Macro Squawk. Click here for the full analysis.
| Take our US midterm election Markets Pulse survey |
|---|
| What will the outcome of US midterm elections mean for stocks and Treasury yields? Let us know . |
| Key Events This Week |
|---|
| For a list, click here. |
Some of the main moves in markets:
Stocks
- S&P 500 futures were little changed as of 7:15 a.m. New York time
- Nasdaq 100 futures fell 0.2%
- Futures on the Dow Jones Industrial Average were little changed
- The Stoxx Europe 600 rose 0.6%
- The MSCI World Index was little changed
Currencies
- The Bloomberg Dollar Spot Index was little changed
- The euro fell 0.2% to $1.1175
- The British pound was little changed at $1.3230
- The Japanese yen fell 0.2% to 158.63 per dollar
Cryptocurrencies
- Bitcoin fell 0.3% to $83,342.85
- Ether rose 0.5% to $2,549.25
Bonds
- The yield on 10-year Treasuries was little changed at 5.24%
- Germany’s 10-year yield declined two basis points to 3.47%
- Britain’s 10-year yield was little changed at 5.43%
Commodities
- West Texas Intermediate crude rose 1.3% to $93.01 a barrel
- Spot gold fell 0.5% to $4,171.83 an ounce
This story was produced with the assistance of Bloomberg Automation.