A sell-off in US government bonds eased after an auction of 10-year Treasuries drew strong demand in a sign that investors were seeking to lock in the highest yields since the turn of the millennium.
US 10-year Treasury yields, a benchmark for borrowing costs in the world’s biggest economy, climbed as high as 5.36 per cent in volatile trading early on Wednesday. But yields fell back sharply after a $39bn auction went smoothly, with the 10-year recently trading at 5.29 per cent.
The strong auction highlights how some investors are snapping up long-term bonds that are paying the juiciest yields in about a quarter of a century following a steep sell-off driven by the surge in fuel prices sparked by the Iran war, rising US growth expectations and vast issuance of debt to fund the AI boom.
“There was a lot of fear going into this auction that demand might be weak,” said Kristina Hooper, chief global macro strategist at Man Group. “It makes sense that seeing strong demand has had an effect. This is a relief rally of sorts.” She cautioned she was sceptical that “the relief can last for long”.
The US government sold $39bn worth of 10-year notes to investors on Wednesday at a high yield of 5.3 per cent. Primary dealers, big banks that are responsible for buying any bonds not absorbed by investors, had the lowest participation rate since 2003 in a sign of the robust demand, according to Vail Hartman at BMO Capital Markets.
US 30-year bonds also recovered following Wednesday’s auction, with yields falling to 5.66 per cent from a high of 5.73 per cent.
John Stopford, head of multi-asset income at Ninety One, said that “if the sell-off carries on much further”, bonds would start to look “meaningfully cheap” and described 30-year Treasuries approaching 6 per cent as a “steal”.
However, in a sign that rates could stay higher for longer, minutes of the Federal Reserve’s latest policy vote indicated the bulk of US rate-setters would back another rise in short-term borrowing costs before the end of the year.
“Most participants assessed that another increase in the target range for the federal funds rate would likely be appropriate by year-end,” the minutes of the September vote said.
Markets are betting the next quarter-point rate rise will come at the central bank’s December policy vote.
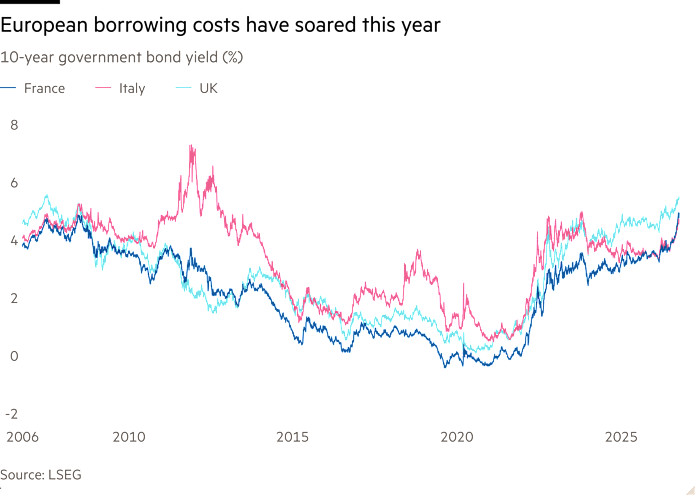
Rising US borrowing costs have also contributed to the gloomy sentiment in global fixed income markets.
European government bonds were under heavy pressure on Wednesday, with French and Italian yields rising more than 0.1 percentage points, extending a series of wild swings.
France’s 10-year borrowing costs rose as high as 4.93 per cent, heading back towards the post-2002 high reached this month, amid persistent worries that the Eurozone’s second-biggest economy was heading for a debt reckoning.
“France might be the first but it won’t be the last,” said Akshay Singal, global head of short-term interest rate trading at Citi.
The UK government debt market was also swept up in the volatile trading, with the yield on the 30-year gilt rising as much as 0.13 percentage points to a 28-year high of 6.04 per cent in afternoon trading in London. It later drifted back to just below 6 per cent.
Singal added: “We hear a lot about the bond vigilantes, especially in the UK, but I think it is really a question of having credible budgetary policies and that’s unfortunately a bit scarce right now globally, and that is what is driving the bond market.”
In currency markets, the euro, which has been hit by concerns over France, was down 0.6 per cent against the dollar. It also touched its lowest level against the pound since mid-2025 in intraday trading.
“French risk is causing fresh idiosyncratic euro underperformance,” said Francesco Pesole, forex strategist at ING.
Additional reporting by Claire Jones in Washington