Britain’s bond market has clawed its way back from the sharpest sell-off among G7 peers in the wake of the Iran war, as investors bet that a low-key Budget next week will keep concerns over the country’s finances at bay.
The UK suffered the biggest jump in borrowing costs among major economies in the initial weeks of the conflict this spring, as traders rapidly switched from expecting interest rate cuts by the Bank of England to betting on multiple rate rises, which weighed on bond prices.
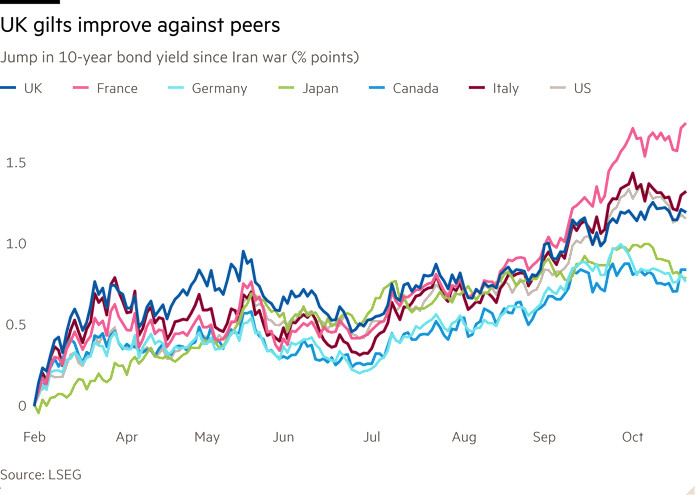
But its stronger relative performance in recent months means it is back in the middle of the G7 pack. The 10-year gilt yield is up just below 1.2 percentage points since the conflict started at 5.41 per cent, whereas Italian yields are up 1.25 points.
In France, which is the new focus of concern for European debt investors owing to the state of its public finances and political uncertainty, borrowing costs have jumped 1.7 percentage points. Bond yields rise as prices fall.
Investors say signals from UK Prime Minister Andy Burnham’s government that it will stick within the economic tramlines of his predecessor Sir Keir Starmer — along with pledges such as scrapping the pensions “triple lock” — have helped calm investors’ nerves ahead of the October 28 announcement.
“The UK has outperformed peers in recent weeks, based on expectations of a low-key first budget, and the market will want to see that confirmed,” said Andrew Chorlton, chief investment officer for fixed income at M&G Investments, adding the firm now has a bigger-than-benchmark position in gilts after the rise in yields.
“This is very much a market where if you can keep your head below the parapet, that is a good thing while there is a lot of volatility,” said Jeff Mueller, co-head of fixed income at Morgan Stanley Investment Management.
Traders are expecting a slimmed-down Budget from chancellor John Healey, with big spending decisions deferred to a spending review next year.
One main focus will be the so-called headroom Healey leaves himself against the government’s self-imposed borrowing limits, which is likely to be eroded by higher borrowing costs and inflation. Fund managers previously told the FT the headroom could shrink to about £14bn, from the £23.6bn in March, without unduly troubling the market.
Some investors warn the UK is only deferring difficult decisions to a spending review next year, amid political pressure to spend more on defence and other priorities. Some see events in France — the worst-performing G7 bond market during the conflict, and under pressure from protesters to boost public spending further — as a timely reminder of the dangers of loosening.
“Pressure on French spreads might serve as a warning to Healey of the dangers of lack of fiscal rectitude,” said Mike Bell, head of market strategy at RBC BlueBay Asset Management. “Fiscal concerns are unlikely to go away.”
The UK’s borrowing costs remain the highest in the G7, reflecting in part sticky inflation as well as elevated levels of borrowing in recent years. But gilt bulls highlight that the UK has a deficit reduction programme that compares favourably with peer economies and it is more a question of whether it can remain on track.
Some point to the political consensus behind avoiding unfunded spending pledges, four years on from the gilts crisis sparked by the ill-fated “mini” Budget of former prime minister Liz Truss.
“Both the Conservative and Labour [parties] have internalised Liz Truss in a way that Germany, France and Japan haven’t,” said one big rates investor. “Both parties [in the UK] are talking about trade-offs in policymaking and the need to fund programmes.”
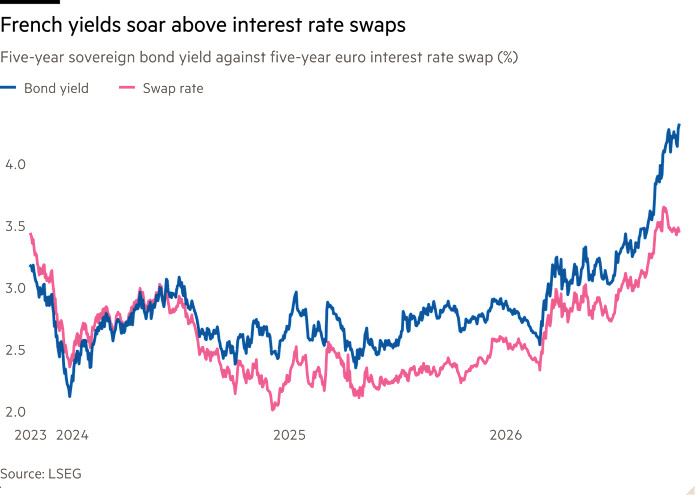
The UK’s five-year gilt yield trades close to the equivalent swap rate, in a sign that investors are not unduly concerned about levels of bond issuance. In contrast, the additional interest rate on the debt compared with euro interest rate swaps has more than doubled this year to more than 0.8 percentage points, around where they peaked in the Eurozone debt crisis.
John Stopford, head of multi-asset income at asset manager Ninety One, described the mood towards the UK as “cautiously constructive, but lots of questions about the mix of spending, tax and borrowing constraints will be balanced over the medium-term”.