Pacific Investment Management Co. says bond yields at multi-decade highs offer attractive income for investors, who should spread their allocations across developed and emerging markets to help protect against fiscal risks.
The money manager, which oversees about $2.33 trillion, unveiled its latest 6- to 12-month cyclical outlook on Tuesday as long-dated Treasury yields hover around the highest since 2002 . The benchmark 10-year note yields about 5.25%, and the 30-year around 5.65%.
Bonds have been slumping since mid-August as the US economy expands amid booming AI infrastructure spending, while steep energy costs keep inflation elevated and sustain the prospect of further Federal Reserve interest-rate hikes this year.
“Attractive starting yields — and the income they can offer — provide a meaningful mitigant against inflationary tail risks while preserving the potential for bonds to hedge a fading AI capex impulse or a shock to growth,” economist Tiffany Wilding and Andrew Balls, the firm’s chief investment officer for global fixed income, said in the report.
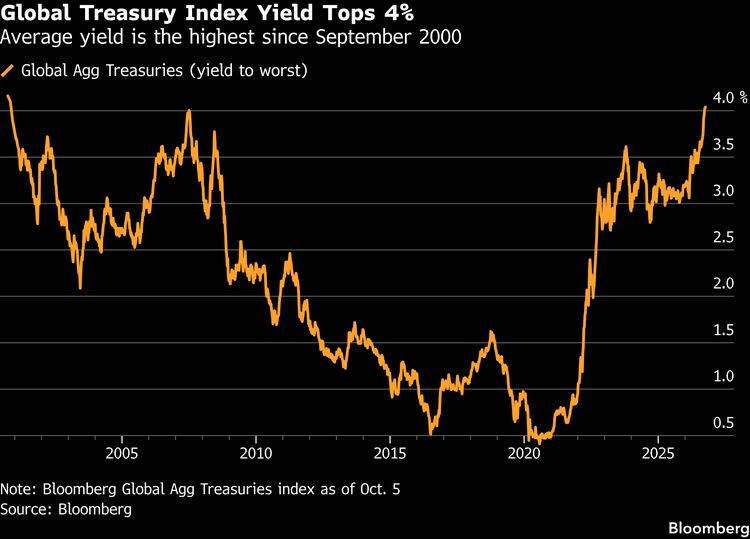
Investors deploying “a global bond portfolio allocation across DM and EM can help diversify country-specific factors, including fiscal risks,” according to Pimco, which is based in Newport Beach, California.
The asset manager says the US and France “stand out with more challenging debt trajectories.” Meanwhile, the likes of “the UK, Italy and Japan remain vulnerable — and Japan increasingly so given recent policies that add to deficits — but their debt trajectories appear sustainable under current fiscal plans.”
Read more: Whispers of Contagion Risk Return to Europe’s Bond Market
Additional fiscal stimulus looms as the main potential driver of higher yields and a steeper yield curve, and “the scale of corporate debt issuance tied to the AI buildout may be a contributing factor,” Pimco said.
While “fiscal concerns will continue to drive episodic market volatility across global markets,” the bond giant said, “investors are getting higher sovereign bond yields than a year ago to help compensate for these risks.
If governments do carry out fiscal adjustments, such as the planned UK budget tightening , yields have room to fall, the money manager said.
In the US Treasury market, Pimco said it still finds five- to seven-year Treasuries attractive and it’s “becoming more constructive on longer-dated bonds as yields rise.” The market has “value for patient investors with an intermediate time horizon,” the firm wrote.
Last month, Dan Ivascyn, chief investment officer at Pimco, said long-term US Treasury yields above 5% are leading the firm to reduce its underweight position on the debt.
Read more: Pimco Trims Underweight on Long US Bonds as Yields Top 5%
US Treasury yields across the 2-, to 10-year area have risen upwards of 50 basis points over the past month, leaving short-dated benchmarks approaching 5%.
September was the worst month for US Treasuries since October 2024, with a Bloomberg index falling about 2.2%.
Pimco offers other points of consideration for the next 6 to 12 months:
- “Higher interest rates will affect a credit default cycle that was already well underway,” and for “corporate direct lending, investors face disappointment relative to returns of recent years”
- The firm says its “yield curve views are becoming more balanced as investors can now find healthy yields across maturities”
- The current AI expansion “is at the heart of the investment opportunity in credit,” and investors should look for “more compensation for regulatory and legal risks and politics tied to the U.S. midterm elections”
- AI disruption for companies favors diversification. “Software is an obvious candidate, but the possibilities are more widespread, and companies that lag in the AI implementation race are at risk of being left behind”
- With more frequent geopolitical, energy, and other supply shocks, investors should consider exposure to commodities and real assets