The financial mood is tense, borrowing costs are rising and dealmaking has been quieter since the summer. But Europe has a cohort of companies that are benefiting from the rise of artificial intelligence, and their animal spirits are stirring. Enter Schneider Electric SE with a surprising and very aggressive $23 billion deal to buy S&P 500 software firm PTC Inc.
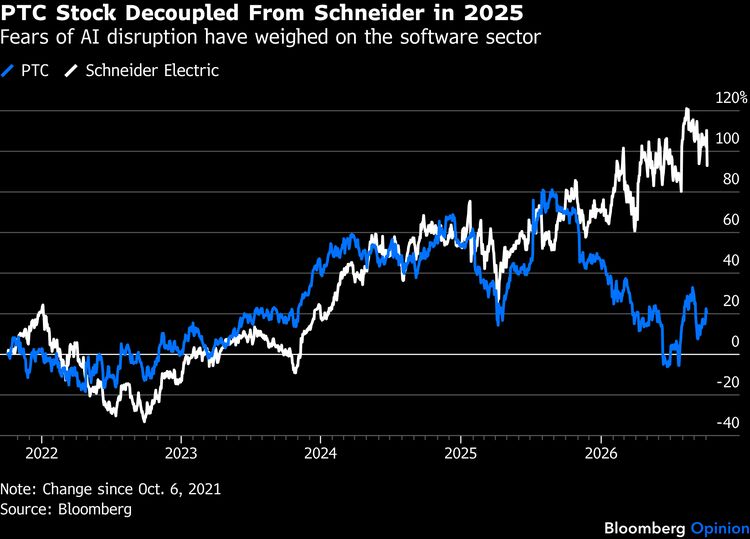
Schneider provides electrical power products and has a sizeable industrial software business. Capitalized at around €160 billion ($179 billion), it has thrived in the data center boom amid demand for energy efficiency. The firm is among the European companies that strategists at UBS Group AG once identified as “AI enablers” and its stock has performed correspondingly well, even if it lacks the glamour of SpaceX or Nvidia Corp.
By contrast, PTC has been on the sharp end of the software sell-off that gathered pace last year before intensifying in February. It has expertise in the computer-aided design of individual products. As of Friday, the stock was down about one-third from its August 2025 peak; its valuation as a multiple of expected earnings had more than halved .
Putting it simply, the deal will give Schneider a more comprehensive software offering spanning the lifecycle of industrial product design and manufacture. Buying PTC has “strong strategic rationale,” say analysts at Jefferies Financial Group Inc.
Financially, this is by no means a cheap transaction. The $205-per-share offer price is 42% higher than PTC’s last close and 5% below its high. Include assumed net debt and the price rises to $24 billion. Schneider says it will take five years for the acquisition to generate returns in line with the cost of capital. PTC is forecast to make only $1.5 billion of operating profit even in 2031, according to forecasts compiled by Bloomberg. The projected cost savings, due after three years, boost that by only $280 million. You can see the need for a long runway.
The buyer seems to be putting a lot of faith in the ability of the pairing to generate more sales combined than separately, forecasting an increase of €800 million without giving a precise timeline. Investors will believe it when they see it.
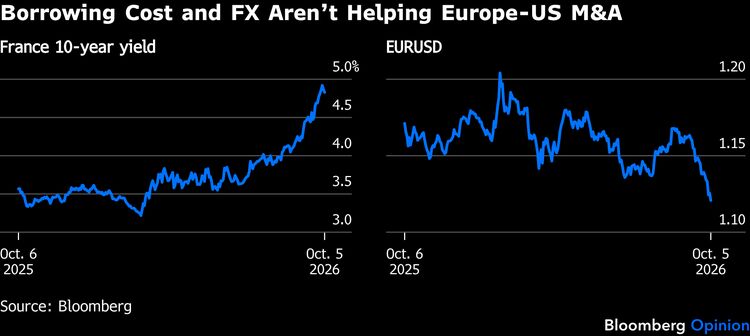
The financing is a stretch too. What a time for a French corporation to be raising between €16 billion and €17 billion of new debt. Of course, Schneider is more global than French, with a strong presence in Asia. But it is still going to be caught up in its host nation’s financial market woes. This deal would doubtless have been cheaper to finance six months ago, when France’s 10-year government bond yield was just above 3.5% rather than nearly 5% and the euro was stronger against the dollar.
Schneider needs to issue stock to raise at least another €5 billion to keep leverage in check. Then there is the worry that the market may be right about PTC’s long-term vulnerability, even if almost all of its current sales comprise so-called recurring revenue. The fact that Schneider Chief Executive Officer Olivier Blum is just two years into the job hardly helps. And analysts at research and advisory firm Oxcap Analytics point out that PTC is a scarce asset that could well attract rival bidders.
Surprise, ambition, leverage and an impending avalanche of new stock. Small wonder Schneider’s share price has reacted badly. There is, nevertheless, one thing that should give investors comfort: Schneider is that rare beast — a company that’s grown successfully by acquisition, including in the US.
Why take such risk? AI beneficiaries seem keen to press their advantage. There may well also be a latent fear among acquisitive bosses that if they don’t pounce on a target soon, one of their rivals will beat them to it. That applies especially in America, given that the current benign antitrust environment may not last forever. Make no mistake, this is a brave deal. This year's M&A splurge clearly isn't over yet.
More from Bloomberg Opinion:
- Oura Just Went Through a $1.5 Billion Health-Check : Chris Hughes
- Can Sam Altman Catch Up While Slowing Down?: Dave Lee
- King Charles Has the Perfect AI Cops for Anthropic and OpenAI : Parmy Olson
Want more Bloomberg Opinion? OPIN <GO>. Or subscribe to our daily newsletter .