A selloff in Singapore bank shares deepened after JPMorgan Chase & Co. warned that surging long bond yields will hurt third-quarter earnings for Southeast Asian lenders.
DBS Group Holdings Ltd. and Oversea-Chinese Banking Corp. fell more than 4% each, while United Overseas Bank Ltd. dropped 5.2%. They were among the biggest drags on the benchmark Straits Times Index, which tumbled 3.5%, the most since April 2025. The index was the worst performer in Asia.
The drop comes after a yearslong rally in Singapore lenders driven by record profits and the city-state’s growing stature as a global wealth hub. That supportive backdrop is now being tested by concerns over the impact of high bond yields on dividend payouts, with valuations elevated.
“What matters is not just where rates are going, but whether asset yields can keep pace with rising funding costs to defend net interest margins,” said James Ooi, market strategist at Tiger Brokers in Singapore. While higher rates can lift yields on loans, banks’ profitability also depends on the levels lenders pay for deposits and other forms of funding, he said.
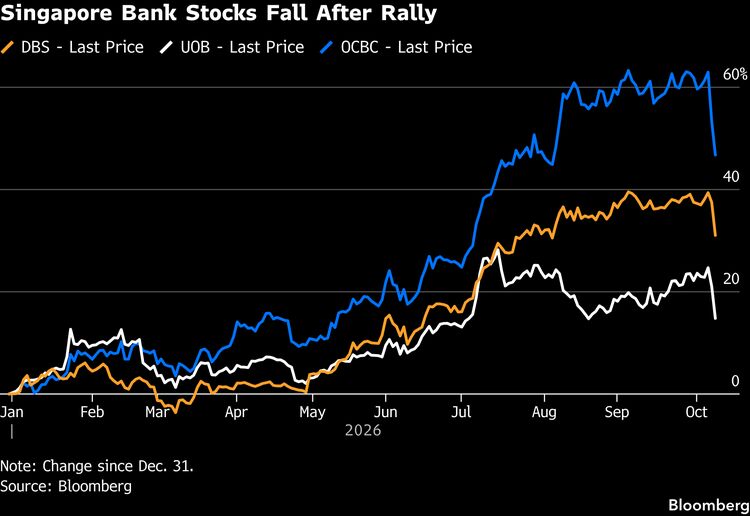
On Wednesday, a JPMorgan analyst said surging long bond yields will lead to higher mark-to-market losses on trading books and hit capital market activity for Southeast Asian banks. In Singapore, slower balance-sheet growth, rising deposit competition and a potential normalization in wealth-management fees could trigger earnings downgrades, with OCBC more at risk.
“The surprise getting into third quarter 2026 is likely skewed negative for quite a few banks under our coverage,” JPMorgan analyst Harsh Wardhan Modi wrote in a note, recommending clients trim their allocations.
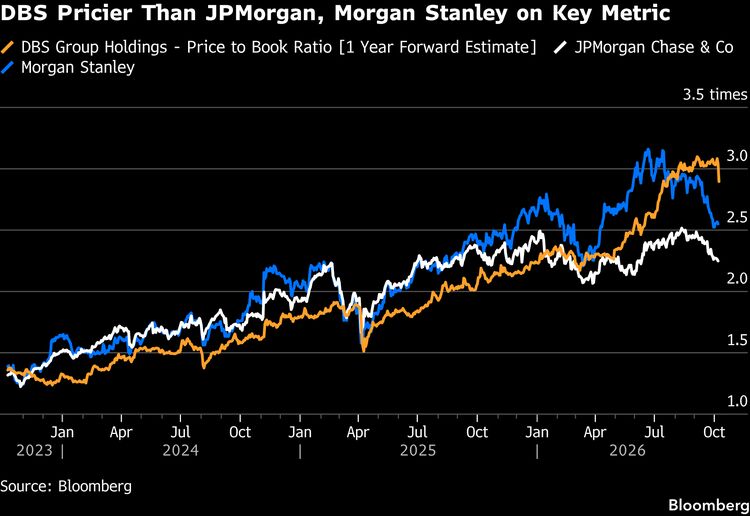
The rally earlier this year also left Singapore banks looking expensive relative to some Wall Street rivals, including Morgan Stanley and Goldman Sachs. DBS, the country’s largest lender, trades at 2.9 times one-year forward book value, nearly double its historical average.
HSBC Holdings Plc downgraded Singapore stocks to neutral from overweight as valuations have become demanding and tighter financial conditions weigh on the real estate sector.
Singapore banks have been the biggest beneficiaries of measures by the Singapore Exchange Ltd. and Monetary Authority of Singapore to improve corporate performance and broaden investor interest, said Kieran Calder, who covers global banks as head of Asia equity research at Union Bancaire Privee. Strong underlying domestic economic growth and banks’ increased focus on fee income also helped, he said.
The selloff has been amplified by a broader rotation out of lenders. Global banks were among the biggest beneficiaries of last quarter’s retreat from artificial intelligence-related stocks, leaving the sector vulnerable as that trade unwinds.
“There are renewed fears of inflation and it would put a dampener on some of the investment cases in some of the banks,” said Nirgunan Tiruchelvam, an analyst at Aletheia Capital. Higher bond yields will put the focus on emerging market sectors facing vulnerabilities, including Singapore banks, he said.