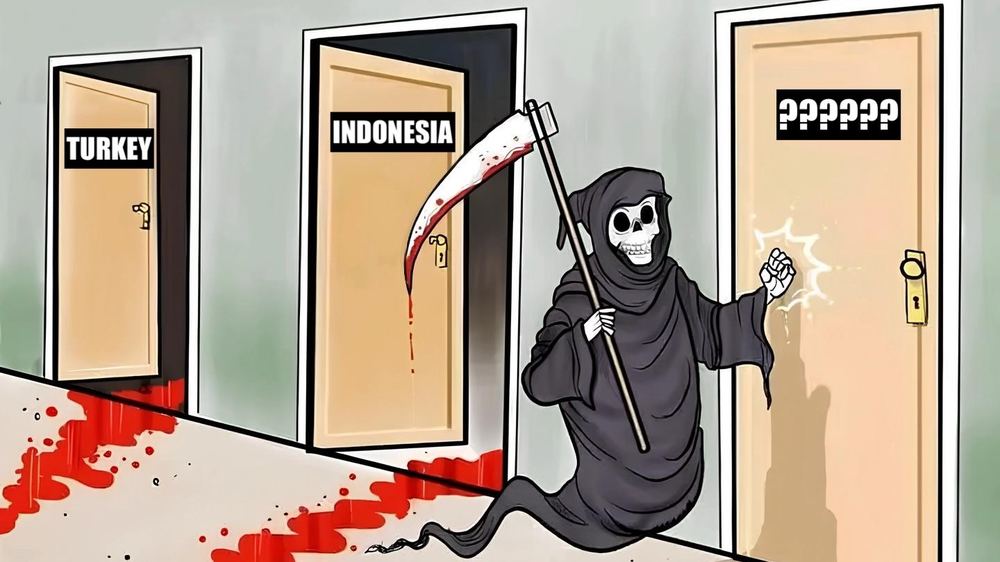
There’s a new force in financial markets, which is scouring the world for countries behaving badly and threatening to cut off their access to international capital if they don’t shape up. And no, we’re not talking about the fabled bond vigilantes.
From mainFT last week:
Indonesia’s stock market tumbled on Friday after global index provider MSCI warned it could exclude the country from its main indices, deepening concerns about investability in south-east Asia’s largest economy.
The country’s benchmark Jakarta Composite Index plunged 11.6 per cent, triggering a trading halt, after MSCI warned it could downgrade Indonesia to standalone market status. MSCI’s indices are closely followed by emerging-market investors and the warning, a significant escalation, could trigger billions of dollars of outflows.
Friday’s fall is the Indonesian market’s largest single-day drop since January 1998, when the country’s stocks were buffeted in the wake of the Asian financial crisis.
Some background might be in order. MSCI is one of the three big dominant global providers of stock market indices, and is particularly influential when it comes to the developing world, where its benchmarks are by far the biggest and most important. The other members of the “Big Three” that dominate the industry are S&P Dow Jones Indices and FTSE Russell.
Financial indices are often seen as mere mathematical reflections of markets. But these benchmarks are also unavoidably subjective, as the companies that compile them decide the conditions for inclusions, exclusions, classifications and weightings. Indexing has consequently become a hugely influential (and enviously profitable) business.
MSCI first suggested that it might downgrade Indonesia from “emerging market” to “frontier market” in January because of well-known issues of opacity, rampant insider trading and market manipulation. However, after talking to big investors — who are widely consulted on inclusions and exclusions — MSCI last week said that even FM status may be too generous.
Here’s the full reclassification consultation proposal, which said:
→ The Indonesian authorities have announced several reforms, including enhanced disclosure of shareholders with ownership above 1%, more granular investor classification disclosure, High Shareholding Concentration (HSC) reporting, and a roadmap towards a minimum free float requirement of 15%
→ However, market participants have indicated that, to date, sufficient progress has not been observed consistently across the Indonesian equity market. Significant concerns remain around market dysfunction, including continued suspected co-ordinated trading behaviour and lack of evidence of meaningful enforcement
Indonesia is an extreme case — as far as Alphaville knows, no major country has ever been ejected straight from “emerging market” to “standalone” status — but MSCI does seem to be baring its teeth more broadly. Turkey is also under review for EM relegation partly because of “possible co-ordinated trading through fund holdings closely affiliated with certain smaller listed companies”.
This is an intriguing development. Index providers regularly review their country classifications, but typically focus on broad issues like the degree of economic development or technical aspects like access and liquidity. The degree of “investability” is a big deal when it comes to grades.
But MSCI’s warnings — and a similar review by S&P Dow Jones Indices for Indonesia and Turkey — indicate that broader issues are now being considered. As Alex Matturri, former CEO of S&P DJI, wrote in MainFT· today:
Recently, index providers seem to be expanding their role to consider factors such as possible market manipulation in determining country classification.
. . . The common thread is a global index provider pushing change where local regulators and exchanges act too slowly. Both cases involve opaque ownership and alleged price manipulation. Encouraging transparency and accessibility is natural for index providers but acting as the market’s surveillance function is a new role.
Indeed, in most countries there will be a financial regulator looking at the exact issues that MSCI raised. At the very least, the local exchange will normally care about its credibility and try to keep shenanigans to a minimum. But when that doesn’t seem to be the case, it is understandable that the index providers take it into account.
After all, although they insist that they are merely providers of investment information — perish the thought that they should be regulated as investment advisers! — the benchmarking companies are extremely aware of the fact that vast sums of money can ebb and flow based on their decisions.
And this isn’t just about passive investing flows either. Traditional active managers also have to take indices extremely seriously, with every investment in practice a short or long relative to the benchmark they are measured against. There is therefore an entire cottage industry of hedge fund strategies that do little but trade around indexing decisions.
Given all this, index providers routinely ask big investors what companies and markets are so iffy that their spots should be reappraised. And it is understandable that they take non-fundamental and technical factors into account. MSCI and its rivals obviously don’t want headlines about how American and European pension plans lost a ton of money because of a mechanistic investment in an obviously dodgy market or company (there’s little anyone can do about the non-obvious ones).
Not everyone is thrilled about the power accruing to humdrum index providers. Here’s a fabulous 2017 Bloomberg story by former Alphavillain Tracy Alloway on the subject, hooked on how Peru had to scramble to prevent a relegation from EM to FM back in 2015 — which could have been calamitous for the country’s access to international capital.
And not everyone thinks that the index providers should embrace a role as a pseudo-market police force. Reuters Breakingviews last week ran a column criticising MSCI for its handling of the Indonesian situation and arguing it should instead throw the “spotlight on a lack of transparency and accountability among powerful index providers”.
This is a longstanding complaint. As a 2021 paper by Johannes Petry, Jan Fichtner and Eelke Heemskerk argued:
Rather than a purely technical exercise, constructing indices is inherently political. Which companies or countries are included into an index or excluded (i.e. receive investment in- or outflows) is based on criteria defined by index providers, thereby setting standards for corporate governance and investor access.
Hence, in this new age of passive asset management index providers are becoming gatekeepers that exert de facto regulatory power and thus may have important effects on corporate governance and the economic policies of countries.
It’s hard not to share some of these misgivings (which I’ve voiced myself before). But when fraud, corruption, cronyism or market manipulation reaches acute levels, it is natural and arguably desirable that the index providers actively play at least a modest gatekeeping role when local regulators and bourses utterly fail to do so.
After all, both Indonesia and Turkey are now desperately trying to address the issues raised by MSCI. “The requests are extremely reasonable,” Turkey’s finance minister Mehmet Şimşek said yesterday. As a result, ordinary Indonesians and Turks might benefit from somewhat cleaner markets.
However, sadly, Alphaville doubts that any of the index providers would be willing to say anything about the current state of US financial regulation and integrity . . .