The writer is former chief executive of S&P Dow Jones Indices
Index providers are a powerful force in the global economy and markets, influencing the flow of investor funds around the world. The recent announcements from MSCI regarding the possible downgrade of both the Indonesian and Turkish markets raise questions on their evolving role.
Historically, the methodologies for country inclusion in an index have been designed to ensure markets are investable for foreign investors. MSCI’s Market Classification Framework focuses on three criteria: economic development, size and liquidity requirements and market accessibility.
Every year, MSCI reviews all global markets and determines whether they should be classified as developed, emerging, frontier or standalone. All the major index providers follow similar, albeit slightly different, approaches to country classification with sometimes drastically different results. The classic case is South Korea, which is classified as a developed market by FTSE Russell but as an emerging market by MSCI. Given the amount of money that tracks indices, such designations have a real impact.
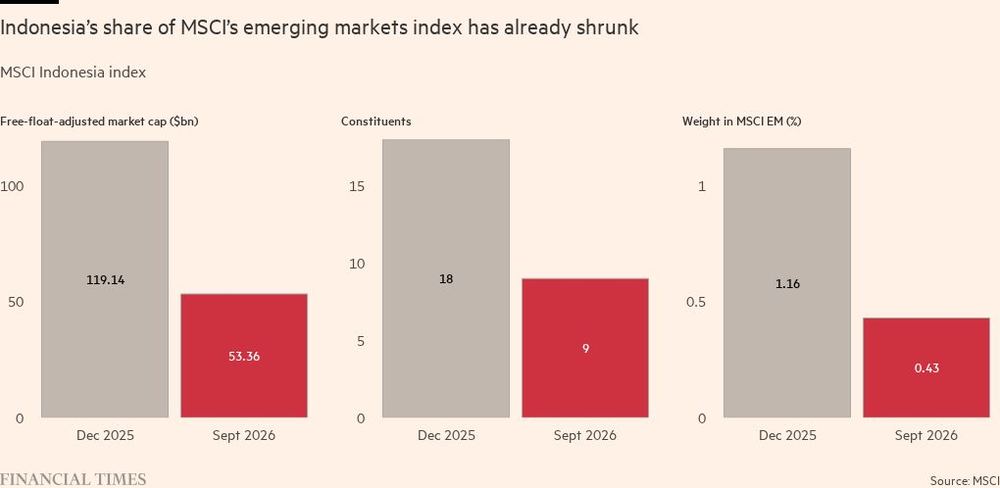
Recently, index providers seem to be expanding their role to consider factors such as possible market manipulation in determining country classification. MSCI raised concerns about “suspected co-ordinated trading behaviour” as one of the reasons for a possible downgrade of Indonesia from emerging to frontier status, in addition to wanting to see improved company ownership data transparency.
S&P Dow Jones Indices is also reviewing both markets, highlighting “disclosure-related concerns and the potential liquidity impact” for Indonesia and “market accessibility challenges and structural concerns, including stock ownership transparency in Turkey, along with the regulatory actions taken by Turkish authorities”.
Data transparency is important to accurately measure the free float — the amount of shares in a company that are available to investors to buy and trade. Index providers adjust the weighting of a company’s shares in an index to this rather than just take into account “total shares”. This is important to ensure an index is not impacted disproportionately by a small amount of trading in a company with limited free float. Underlying the concerns in Indonesia was the potential for market manipulation, which has been recognised by OJK, the Indonesian regulator.
Indonesia seemed on its way to a resolution. There is new leadership at the regulator and the Indonesian Stock Exchange, a higher free-float requirement, and new ownership disclosure rules. Despite these changes, according to MSCI, market participants feel sufficient progress has not been made.
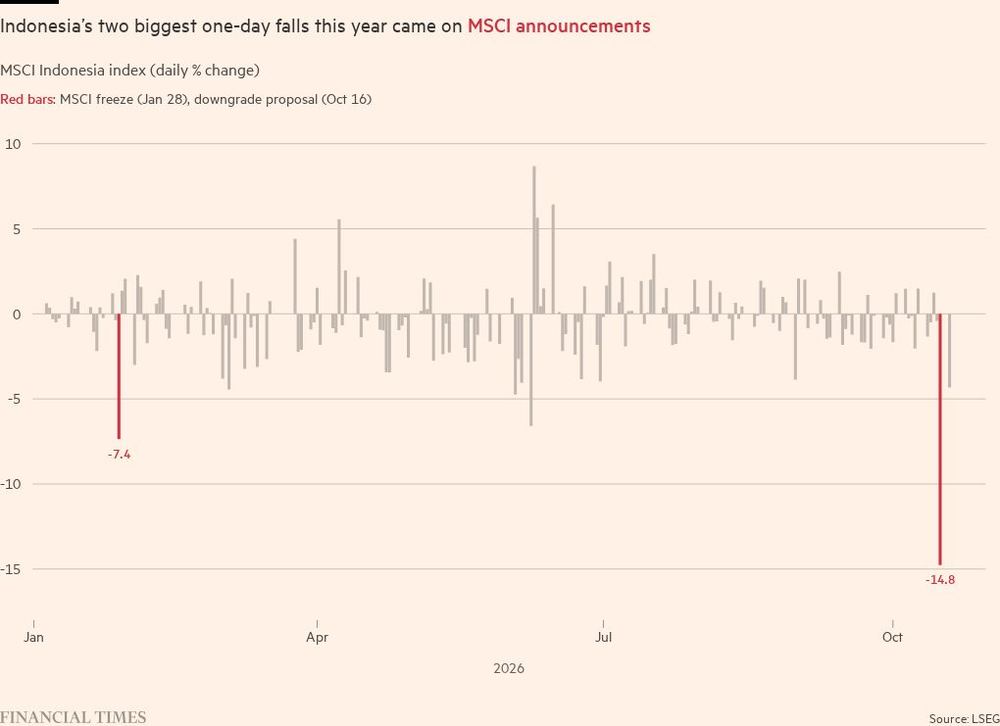
Last week, MSCI launched a consultation to reclassify Indonesia from emerging market to standalone status. Standalone status can be a big blow for a country as it is excluded from indices used by investors.
MSCI said a frontier downgrade would not properly recognise the depth of the market’s problems. The Jakarta Composite fell more than 11 per cent on Friday in response. Turkey received a similar warning the same day. MSCI froze some index changes and flagged a possible reclassification. This follows allegations that investment funds manipulated low-float stocks to inflate returns. The fallout in Turkey from the allegations has included arrests and the liquidation of 131 funds by the local regulator.
The common thread is a global index provider pushing change where local regulators and exchanges act too slowly. Both cases involve opaque ownership and alleged price manipulation. Encouraging transparency and accessibility is natural for index providers but acting as the market’s surveillance function is a new role.
The root problem may be the standing and power of the regulator itself in emerging markets. But the fix must be driven locally. An index provider can help drive transparency and listen to market participants through its formal consultation process, but its only real recourse is a downgrade.
MSCI can be acting with the best of intentions but in the end, market regulators are in the best position to drive change in how markets function. They can impose fines, ban participants and change regulations.
Index providers play an important role in providing transparency and opening markets to foreign investors, but when it comes to situations involving potential market manipulation, this becomes a slippery slope and hard to reconcile with existing methodologies.