Have some Twix-flavoured protein with your overnight oats? A surge in demand for muscle-building products, including brand collaborations, is sparking new interest in one-time investor darling THG, owner of the Myprotein brand. After trying its hand as a tech pioneer, the group is returning to its retail roots, this time with extra bulk.
THG has been a controversial pick since its London float six years ago, first for its undemocratic governance — founder Matthew Moulding only gave up his takeover veto power in 2023 — then for its plunging share price. Investors lost confidence that its supposed crown jewel, an ecommerce platform called Ingenuity, could ever generate the sales they’d initially hoped for.
While THG’s shares are down a disastrous 90 per cent since going public, they have jumped a quarter in the past week after the company said it was on track to deliver its first year of positive free cash flow since floating and nudged up its full-year ebitda forecast. Analysts now expect £103mn, 4 per cent ahead of previous predictions.
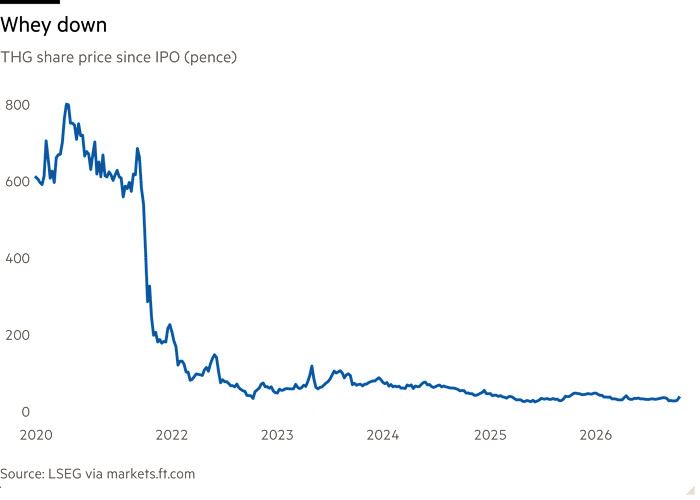
Shorn of Ingenuity — distributed to participating shareholders in 2025 at a fraction of its 2021 heyday valuation — THG is focused on two businesses, both with generally attractive prospects. The first is beauty, operating the Lookfantastic and Cult Beauty websites selling premium brands. The bigger slug of interest, though, has been fuelled by its nutrition division, buoyed by the trend for adding protein to everything from coffee to crisps.
In the short term, surging whey prices have eaten into margins and forced all producers, including THG, to look at reformulating products with other sources of protein. Peel Hunt analysts forecast an ebitda margin for the whole of THG of 7 per cent for 2026 but believe that can reach 13 per cent in more normal times.
THG still has a lot to prove. Protein supplements may well become a commodity as newbies shop around, lacking loyalties to gyms or bodybuilding communities. Myprotein’s established brand is, however, some protection, supported by its tie-ups with Müller yoghurts, Krispy Kreme and Mars, among others. Moulding’s unconventional style — including past broadsides against hedge funds and short sellers — adds another unusual risk.
Thicker-skinned investors may be most concerned that THG has undershot analyst forecasts for the past four years, according to S&P Capital IQ. That gap has shrunk at least. Like a Müller Myprotein Crunch Vanilla Flavour Yoghurt at the end of a tough workout, sustainable success for THG might taste better for all the pain that’s gone before.