The S&P 500 is set to bounce back from two days of losses as oil prices fell and worries over the sustainability of the artificial-intelligence investment boom receded.
Futures for the US benchmark rose 0.4%, while Nasdaq 100 contracts climbed 0.8%. OpenAI expects to reach or exceed $70 billion in annualized revenue · by year-end, according to people familiar with the matter, helping ease concerns that its sales were falling short of earlier estimates. An exchange-traded fund tracking chipmakers rebounded 1.7% in US premarket trading.
Brent crude slid below $103 a barrel after President Donald Trump said the US would not attack Iran before the midterm elections. He also cited “productive discussions” with Tehran. The benchmark hit a two-week high in the previous session over fears that an escalation in the Middle East could be imminent.
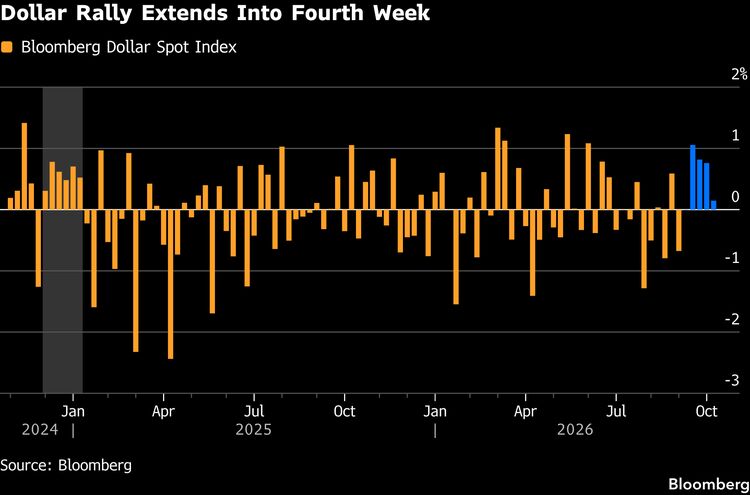
Treasuries resumed losses following a turbulent session that ended with yields retreating from multidecade highs. Ten-year yields rose two basis points to 5.25% on Friday. The dollar was muted, though remained on course for a fourth straight weekly gain.
Higher crude prices have acted as a brake on equities by keeping pressure on interest-rate expectations, offsetting some support from robust corporate profits that have pushed the S&P 500 to a record high. And while optimism over AI remains intact, there’s little certainty about which companies will ultimately capture the profits, particularly as borrowing costs rise.
“The key risk for the AI trade is not necessarily a collapse in demand, but rather a gradual moderation in growth or monetization that falls short of the market’s increasingly ambitious assumptions,” said Francisco Simon at Santander AM. “Even incremental information can trigger an outsized response.”
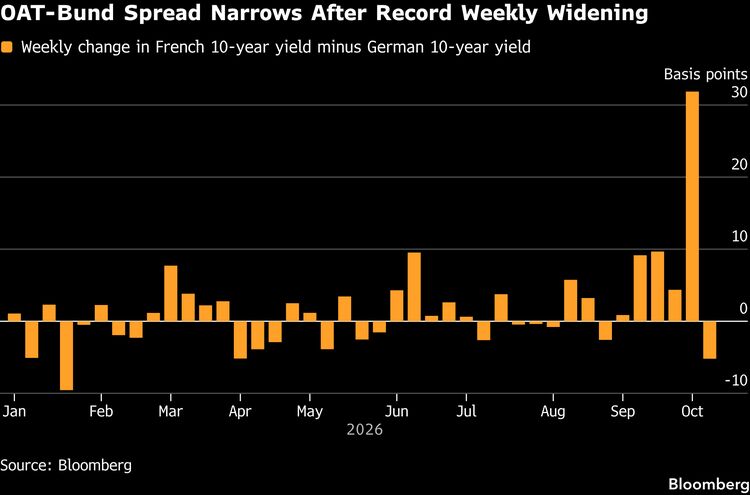
Europe’s Stoxx 600 rose 1%, erasing losses of as much as 1.3% for the week. The region’s bonds rallied, tracking gains late in the US session, with French securities outperforming. The moves come at the end of a week in which France was the focal point of worries over fiscal pressures and political gridlock.
With US big banks set to unofficially kick off third-quarter earnings season next week, stocks will be increasingly driven by earnings delivery rather than macro uncertainty, according to Santiago Mateo Yanguas at CaixaBank AM.
Corporate results “will ultimately determine whether strong fundamentals can continue to justify current valuations,” he said.
A mild correction in September has brought stock valuations back to reasonable levels, suggesting earnings season should provide support for markets, said Mary-Sol Michel at Swiss Life Banque Privée.
“We expect the AI trade to continue to be the main driver, and that’s illustrated by the impact of OpenAI’s revenue update,” she said. “Of course, rising oil prices are fueling inflation and lifting bond yields, but this backdrop is somewhat expected to pause as we get closer to the midterms.”
| Take our US midterm election Markets Pulse survey |
|---|
| Which of President Donald Trump’s policies stand to benefit US assets most after midterms and which put them most at risk? Let us know . |
Corporate News:
- Firmus Grid Ltd. · is exploring a private funding round to raise as much as $3 billion after the collapse of its planned initial public offering left the data center operator looking for other financing options.
- Mobile payments firm Airtel Money is set to start trading on the London Stock Exchange later on Friday, a listing that may mark the largest initial public offering for the bourse in five years.
- SoftBank Group Corp. · seeks to raise as much as $100 billion from Gulf investors to help it amp up its bets on AI, the Financial Times said.
- Elon Musk · ’s SpaceX said it acquired low-band spectrum that will enable it to use its Starlink satellites to become a “major mobile carrier” in the US, sending shares in incumbent cell providers falling as much as 8%.
| Key Events This Week |
|---|
| For a list, click here. |
Some of the main moves in markets:
Stocks
- The Stoxx Europe 600 rose 1% as of 10:56 a.m. London time
- S&P 500 futures rose 0.4%
- Nasdaq 100 futures rose 0.8%
- Futures on the Dow Jones Industrial Average rose 0.1%
- The MSCI Asia Pacific Index rose 0.4%
- The MSCI Emerging Markets Index rose 0.5%
Currencies
- The Bloomberg Dollar Spot Index was little changed
- The euro was little changed at $1.1220
- The Japanese yen fell 0.3% to 158.29 per dollar
- The offshore yuan rose 0.2% to 6.6918 per dollar
- The British pound was little changed at $1.3240
Cryptocurrencies
- Bitcoin rose 1% to $82,599.96
- Ether rose 1.1% to $2,501.46
Bonds
- The yield on 10-year Treasuries advanced two basis points to 5.25%
- Germany’s 10-year yield declined two basis points to 3.48%
- Britain’s 10-year yield declined four basis points to 5.44%
Commodities
- Brent crude fell 1.3% to $102.95 a barrel
- Spot gold rose 1.3% to $4,187.56 an ounce
This story was produced with the assistance of Bloomberg Automation.